Can Japan pass the baton? Venture capital meets the succession crunch
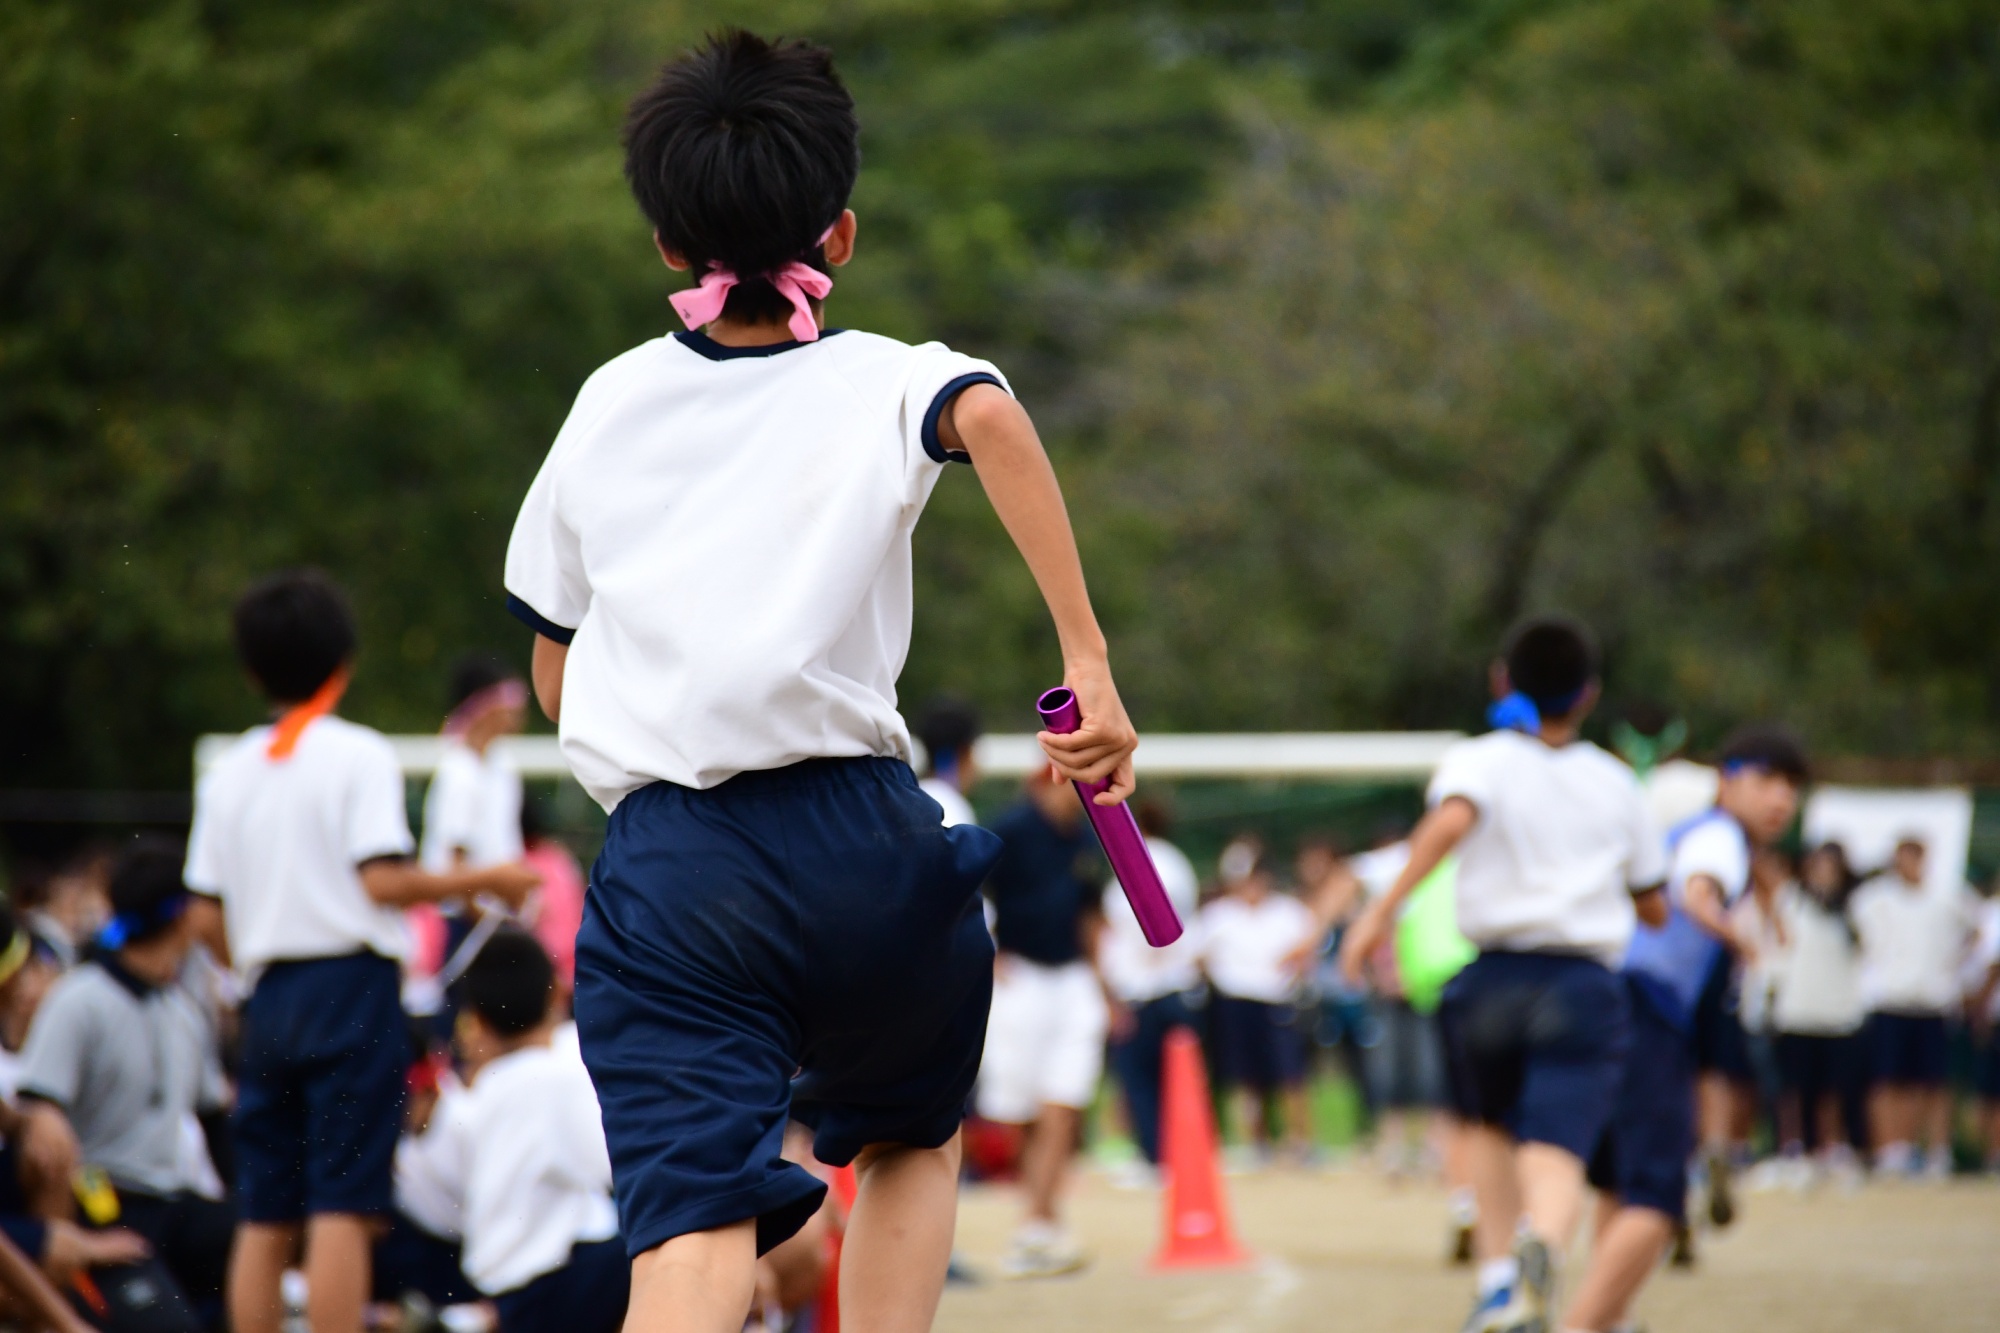
Japan’s SMEs are running a relay race, but many are struggling to find someone to take the baton.
In July, Japan recorded just over 1,000 bankruptcy cases, marking the second consecutive month above that threshold. High prices and labour shortages were among the biggest corporate pressures, but another long-running Japanese problem also played a role: finding a proper successor to the business.
Oddly enough, this is happening at a time when Japan has an abundance of cash looking for the next big business to invest in. That makes Japan’s current experiment with venture capital (VC) as well as mergers and acquisitions (M&A) more than a startup story – it is increasingly becoming a succession protocol as well.
More money, more deals
Investment in Japanese startups increased more than thirteenfold within a decade, from JPY 64.5 billion (USD 414.2 million) in 2012 to JPY 877 billion (USD 5.6 billion) in 2022. Foreign VC firms have also become increasingly active in a market domestic investors once largely dominated. The rise, however, looks less like a lucky ride on the global venture capital shinkansen (bullet train) and more of an uphill climb as it coincides with a series of deliberate reforms aimed at making Japanese companies, capital markets, and investors more willing to take on risks.
Japan’s VC market has therefore grown considerably, although it still lags behind some of its regional peers. Graph 1 shows Japanese VC investment rising from 0.018 per cent of GDP in 2009 to 0.056 percent in 2024. Although the number looks small, it represents a more than threefold increase in VC investment relative to the size of the economy. In absolute terms, investment increased from about JPY 149.2 billion (USD 935 million) in 2009 to roughly JPY 366.99 billion (USD 2.3 billion) in 2024.

South Korea, however, has been running a faster race, having increased VC investments from 0.04 per cent of GDP in 2009 to almost 0.14 per cent in 2024. At its peak, it reached around 0.24 per cent of GDP, more than four times Japan’s level. Both markets have subsequently cooled, but Korea’s VC intensity remained roughly 2.5 times Japan’s in 2024.
The broader startup investment figures capture more than the Organisation for Economic Co-operation and Development’s narrower VC definition, but both point in the same direction: Japan may still be playing catch-up, but its startup financing ecosystem has expanded markedly.
Government push
With the Startup Development Five-Year Plan, the Japanese government is setting a rather ambitious goal of raising annual startup investment from around JPY 800 billion (USD 5.15 billion) to approximately JPY 10 trillion (USD 64 billion) by fiscal year 2027. Japan may need more than a lucky charm to get there, but the target represents the government’s policy direction: more funding, more startups, and importantly, more ways for investors to eventually get their money out.
One sign that the broader corporate market is responding is Japan’s increasingly active M&A market. Deal activity strengthened sharply in 2025 with 5,115 transactions involving Japanese companies, up 8.8 per cent from 2024. Meanwhile, deal value rose even faster by almost 75 per cent, amounting to JPY 35.7 trillion (USD 229.8 billion) covering more than 4,000 domestic deals.
This does not mean that an ageing owner of a small and medium-sized enterprise (SME) can simply put up a “for sale” sign and expect buyers to queue outside the factory gate. Instead, the data suggest that buying, selling, and restructuring companies is becoming the norm in Japanese corporate life. Governance reforms have helped nudge that change, with takeover rules placing greater emphasis on credible acquisition offers, corporate value, and shareholder interests.
For SMEs looking beyond family succession, that broader change in attitude towards M&A may eventually matter as much as VC growth. As for SME owners without a willing heir, selling can increasingly provide a means for succession rather than simply an exit strategy.
Who takes the baton?
Japan’s SME succession story is changing, although not in the way one might expect. The tradition wherein children or other relatives inherit businesses appears to be weakening – not to mention, some owners may have no next of kin to begin with. Graph 2 shows that the share of incorporated SMEs considering family succession fell from about 33.7 per cent in 2018 to 29.5 per cent in 2025.

It may look like Japan is moving beyond hereditary succession, however, the baton is not necessarily being passed elsewhere. The combined share of firms considering transferring their business to another company or individual was only 2.3 per cent in both periods. Meanwhile, those who have yet to consider any succession plan grew from 40.1 per cent to 44.5 per cent.
That makes Japan’s SME ownership landscape more complicated. Although family succession is becoming less dominant, market-based succession has not rushed in to fill the gap. Instead, many businesses appear to be postponing the inevitable.
Unfortunately, time may be less willing to wait. Survey shows that around 53 per cent of SME presidents are already aged 60 or older, and other estimates suggest that about 1.27 million small business owners are over age 70. Japanese SMEs therefore face an awkward management handover wherein the traditional family route is weakening before a sufficiently deep capital market is developed. The latter would have enabled the takeover by professional, outsider successors.
This is where VC itself reaches its limit. A traditional VC fund is unlikely to rescue a decades-old regional manufacturer just because its owner has no heir. However, the broader venture capital and business acquisitions environment – including private equity, search funds, management buyouts, and acquisition finance – can help. Japan’s succession problem may depend less on producing more venture capitalists and more on building a deeper market for transferring business ownership.
For years, Japan has tried to channel more capital into young companies. The next challenge may be getting new owners into old ones. If governance reform, VC, and M&A can make SME ownership easier to transfer, the same reforms helping young firms grow may also keep viable older ones alive. Passing the baton is still the hard part.
This original article has been produced in-house for Lundgreen’s Investor Insights by on-the-ground contributors of the region. The insight provided is informed with accurate data from reliable sources and has gone through various processes to ensure that the information upholds the integrity and values of the Lundgreen’s brand.