The Eurozone fiscal quake is a reality
Germany has moved towards political chaos on the provincial and national level while France’s budget negotiations may explode. These build up nervousness among both investors and consumers in the Eurozone.
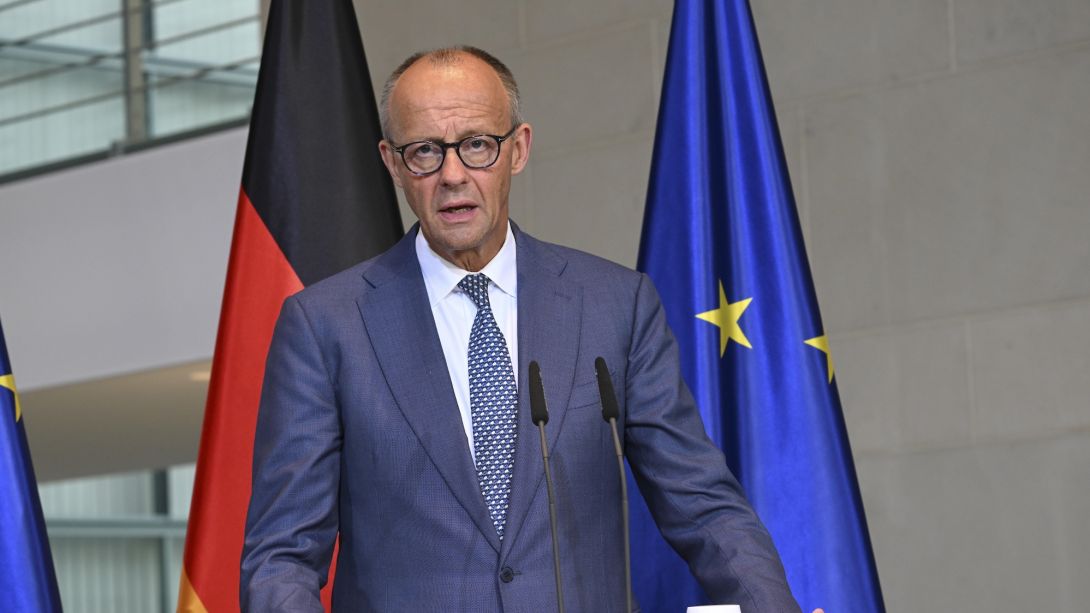
German Chancellor Friedrich Merz has been hit by a political autumn voting storm as his party, the conservative Christian Democratic Union (CDU), lost in two small states, Saxony-Anhalt and Mecklenburg-Western Pomerania. Especially for the party itself, the surprise was how big the losses turned out to be as CDU was even ejected out of Mecklenburg-Western Pomerania’s parliament. One could ask if two elections in two small German states can really influence the financial markets. The answer is yes, and the same may happen in Paris.
Of course, the key factor is the political stability in Germany – or the lack of it. Though Merz’s close allies are still backing him up, the reality is that he can hardly fight his way back. The only reason why Merz still has his title is that the real CDU contender represents the same politics, just canned in a different way.
Meanwhile, the government’s junior partner, the Social Democratic Party, also suffers from internal restlessness since this summer. The nervousness comes from the so-called reforms that Merz and CDU are proposing. We conclude, once again, that what is labelled as reforms in Germany are hardly reforms and that this government represents a political standstill.
Eyes on France, too
Though there is no direct link between Germany’s current political weather and French politics, both situations originate from the same source: a lack of positive change and genuine political reform work.
Currently, France is gearing up for the presidential election that will probably be decided in May next year. The uprun even seems to generate more political havoc than expected. As France needs to badly cut the budget deficit, the current government has proposed a spending cut of EUR 54 billion. Though, we expect that majority of the contenders in the presidential election will try to please the voters in the short-term by simply rejecting the budget cuts. Unfortunately, this will drive the French credit spread even higher in the bond market.
On 23 September, left-wing candidate Jean-Luc Mélenchon topped up by suggesting that France should cancel EUR 455 billion worth of French government bonds held by the Banque de France. As he says, nobody will feel it, but it will reduce the public debt-to-GDP ratio by a substantial 14 percentage points.
No doubt, that it would be equivalent to a default and will leave a hole at the central bank that needs to be filled. This kind of thinking can really move the financial markets towards fear.
Minimal gains ahead
Though the developments in Germany and France are very different, these are happening at the same time. From a market perspective, both are negative events, and this is why we give it extra attention. After all, these are the two biggest economies in the Eurozone, though not all developments are pointing in the wrong direction.
GDP growth forecasts in the Eurozone are getting upgraded, with Germany gaining the most. However, it is predominately caused by defence spending which is equal to public spending. This is simply not satisfactory as it is not healthy growth.

Healthy growth has been severely missing in France for almost a whole generation. Graph 1 shows that while the government budget has been in a persistently significant deficit, the last years were truly bad, reaching more than 5 per cent of GDP. This has led to growing concern among the general population.
The mix of lacking healthy political strategies and rising uncertainties on public finances almost always leads to private households and consumers holding back on spending or simply getting nervous. Many statistics show that this is the case in the Eurozone, such as that seen in Graph 2 which illustrates consumer confidence in the EU. When it comes to France and Germany, as well as in other countries, we hardly expect an improvement until mid-next year.

Oncoming ruptures
So, does our concern mean we expect the European stock market to crash by 20 per cent during the fourth quarter?
This is certainly not our main scenario. Right now, we are still arguing for an overweight risk on a global level. Concerning the Eurozone, our years-long recommendation of an underweight risk is now partially due to the concerns raised in this article.
Our main concern is fundamentally the rising yields on government debt. Despite the current elevated inflation that is also pushing bond yields higher, we are focusing on the longer trend where yields have continuously moved upwards. We consider this as a widening of credit spreads for French and German government bonds. That is, investors are demanding a higher risk premium for financing the debt. In particular, for France, this has become a painful cost in the fiscal budget.
The rising credit spread is also a clear signal of an unhealthy public fiscal situation which, in the long run, can create instability. This is the major reason why it makes sense for investors to spend time on this development in the bond markets: instability risk includes higher volatility across the financial markets and causes rollercoaster movements.
Circling back on concerns about the stock markets, we are prepared for higher volatility in the coming fourth quarter. We are considering the risk for a sell-off in stocks but it is not the primary scenario right now. But we have an increasing number of our wealth clients who have been asking about shifting from stocks to bonds. It is a classical consideration among investors, and is likewise well-known on Wall Street, that the 10-year US Treasury yield becomes a competitor to stocks. The discussion emerges whenever the 10- year Treasury yield competes with the average dividend for the S&P 500 index.
We are very observant of this market movement because this can change our short-term to mid-term view on stocks. Should the shift from stocks to bonds explode, then we expect the move to be steep but it would not be a long-lasting downturn. The simple reason is that government bonds represent a rising risk where many companies and stock markets are very healthy. This is a main reason why we so far keep our overweight risk recommendation. Though this is the case for most of the world, it is not for the Eurozone for obvious reasons.