Looking beyond China’s tech stocks
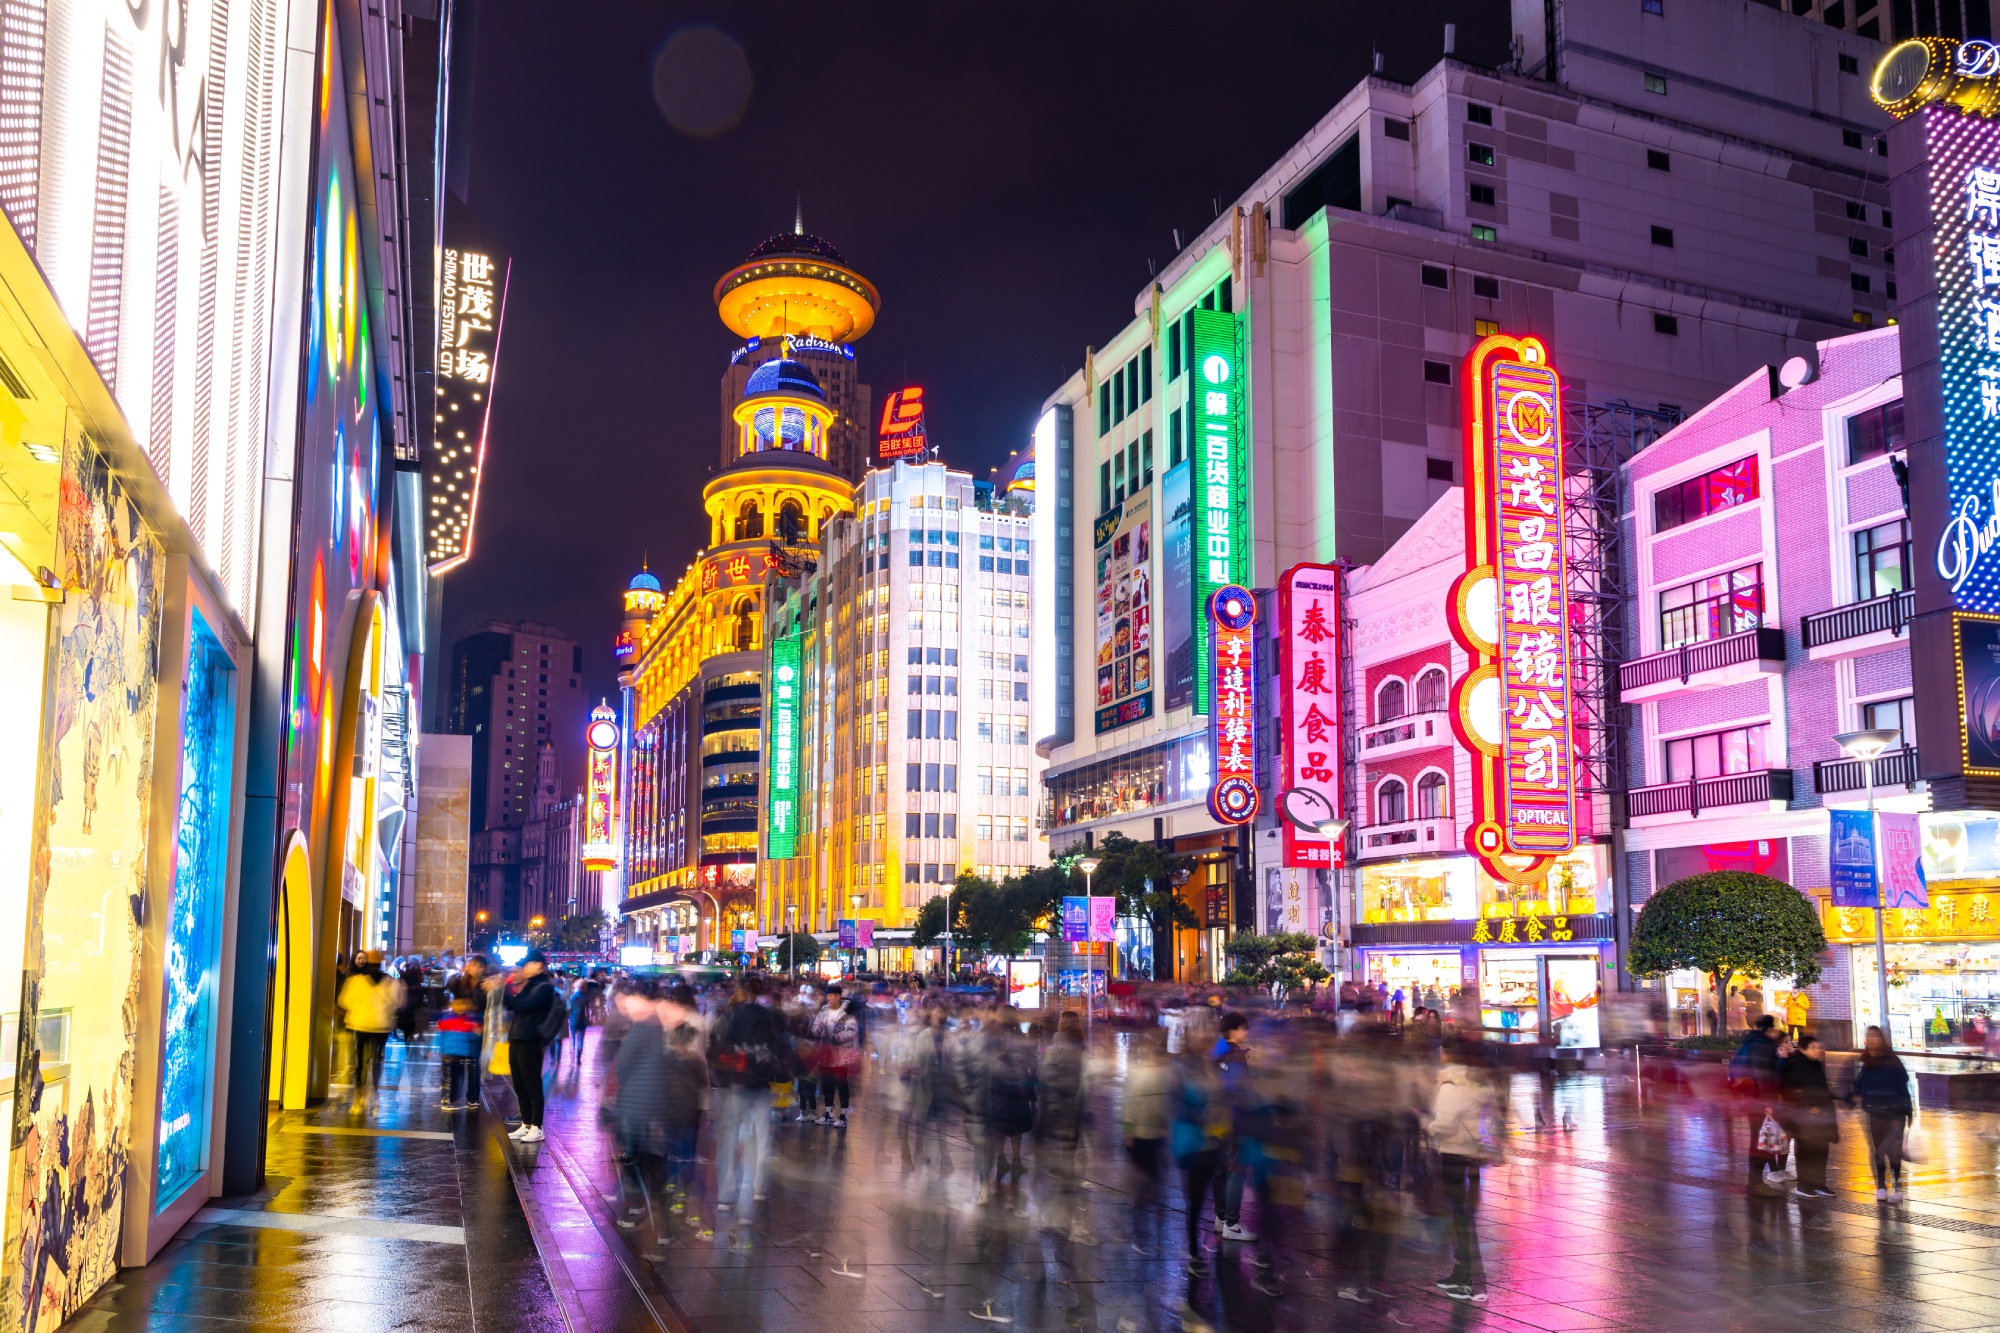
Chinese equities have not been spared by a global tech sell-off, but we find opportunities in other sectors that have lent strength to overall stock market performance in the past quarter.
Stock market investors have been so keenly focused on high-technology companies since 2025, and for good reason.
Advancements in the artificial intelligence (AI) space have provided the biggest boost to global indices, including China equities, which have continued to do so until a global sell-off began in June and deepened in July-September. This about turn in global tech optimism, coupled with persistently weak domestic consumption in Mainland China, has interrupted the rapid momentum of Chinese stocks thus far. However, we at Lundgreen’s remain upbeat about opportunities among local listed companies, including non-tech sectors.
Eyes beyond AI
Given China’s current economic context, among the exciting segments within the Mainland market are currently healthcare and financials. Specifically, there is a steadily growing demand for elderly care as China’s old-age population climbs. Combined with a decelerating birth rate, this creates new opportunities within the healthcare industry.
Graph 1 captures the steady growth in health-related shares under the Shanghai Stock Exchange (SSE), which climbed 4.3 per cent year-to-date.

Demand for health products and medical care services is expected to have constant growth over the coming decades as China’s demographic shift progresses further, signalling that the national government’s childbearing incentives are doing little to reverse the country’s population decline. As an example, there are companies which have since shifted beyond baby care products to include items for geriatric needs, such as offering both infant and elderly formula milk and diapers, dietary supplements, and other personal care items.
The performance of the SSE’s healthcare sub-index may not be as upbeat as its counterparts, but we anticipate that growth within this segment would be more stable in the medium term. This, together with investing in shares within the financial sector, serve as a hedge against over-reliance and overexposure to the highly volatile tech sector.
There is also reason to stay bullish about discretionary consumer spending, with this sub-index rising 26 per cent year-to-date. Despite tepid overall demand, there are pockets of opportunity within the mid-market or mid-range segments. There is evidence that Chinese consumers are not completely gone; instead, they have only been staying away from luxury purchases. Domestic financial conditions have remained largely supportive of household spending as interest rates have been kept at an all-time low since 2025 and as credit and liquidity conditions stay ample.
Repositioning
The combined effect of profit-taking, AI credit fatigue on Wall Street, and safety concerns regarding the speed and breadth of AI development are fuelling the global tech sell-off. However, we find that many of these concerns are US-focused – instead, one should consider opportunities outside Silicon Valley.
Graph 2 shows that a fourth of projected capital expenditure requirements for the global data centre buildout is located within Asia Pacific, which PwC estimates to be worth USD 8.2 trillion until 2050. Another USD 7 trillion in capex for new data centres is projected for Europe, Middle East, and Africa, and these numbers are likely to rise with faster adoption of AI-enabled innovations in these regions.

In our view, the immense infrastructure requirements for the global data centre buildout confirm that there is plenty of room for AI-related growth outside of the US. Together with the fact that nearly 60 per cent of the world’s population reside in Asia, these further build confidence in investing in listed tech companies in the region, including China.
The recent tech sell-off is not a flashing exit sign; rather, it is a chance to buy the dip and recalibrate investment positions for diversification. This has been our strategy in our own Lundgreen’s Invest – China Fund, where we have temporarily held a bigger chunk of the portfolio in cash as of end-September in anticipation of opportune entry points in Chinese firms listed on the Hong Kong and US exchanges.
We maintain our view that China equities are largely undervalued for both tech and non-tech shares, more so now that stock prices have been declining. Still, we see China remaining on an upbeat growth path in the years ahead, and this will help prop up consumer and industrial demand for goods and services.
This year has been a stormy one for China stocks, yet over 170 companies found it a good time to pursue their initial public offerings (IPOs) in the Hong Kong and China exchanges according to data from PitchBook, a Morningstar company. One-third of these listings are tech companies. Still, there is room to be selective as more IPOs trickle in: a track record of earnings and a robust pipeline of new orders are generally encouraging amid a highly unpredictable global market. The very same considerations form part of our investment decisions concerning China equities as we keep a close watch on various macro and industry-level developments that shape the stock market outlook.
Some of the views expressed in this article have been discussed during the China Fund Quarterly Webinar hosted by Lundgreen’s Invest with Yiyi Capital, a Hong Kong-based China specialist, held on 20 October 2026.