AI fatigue? China is just getting started
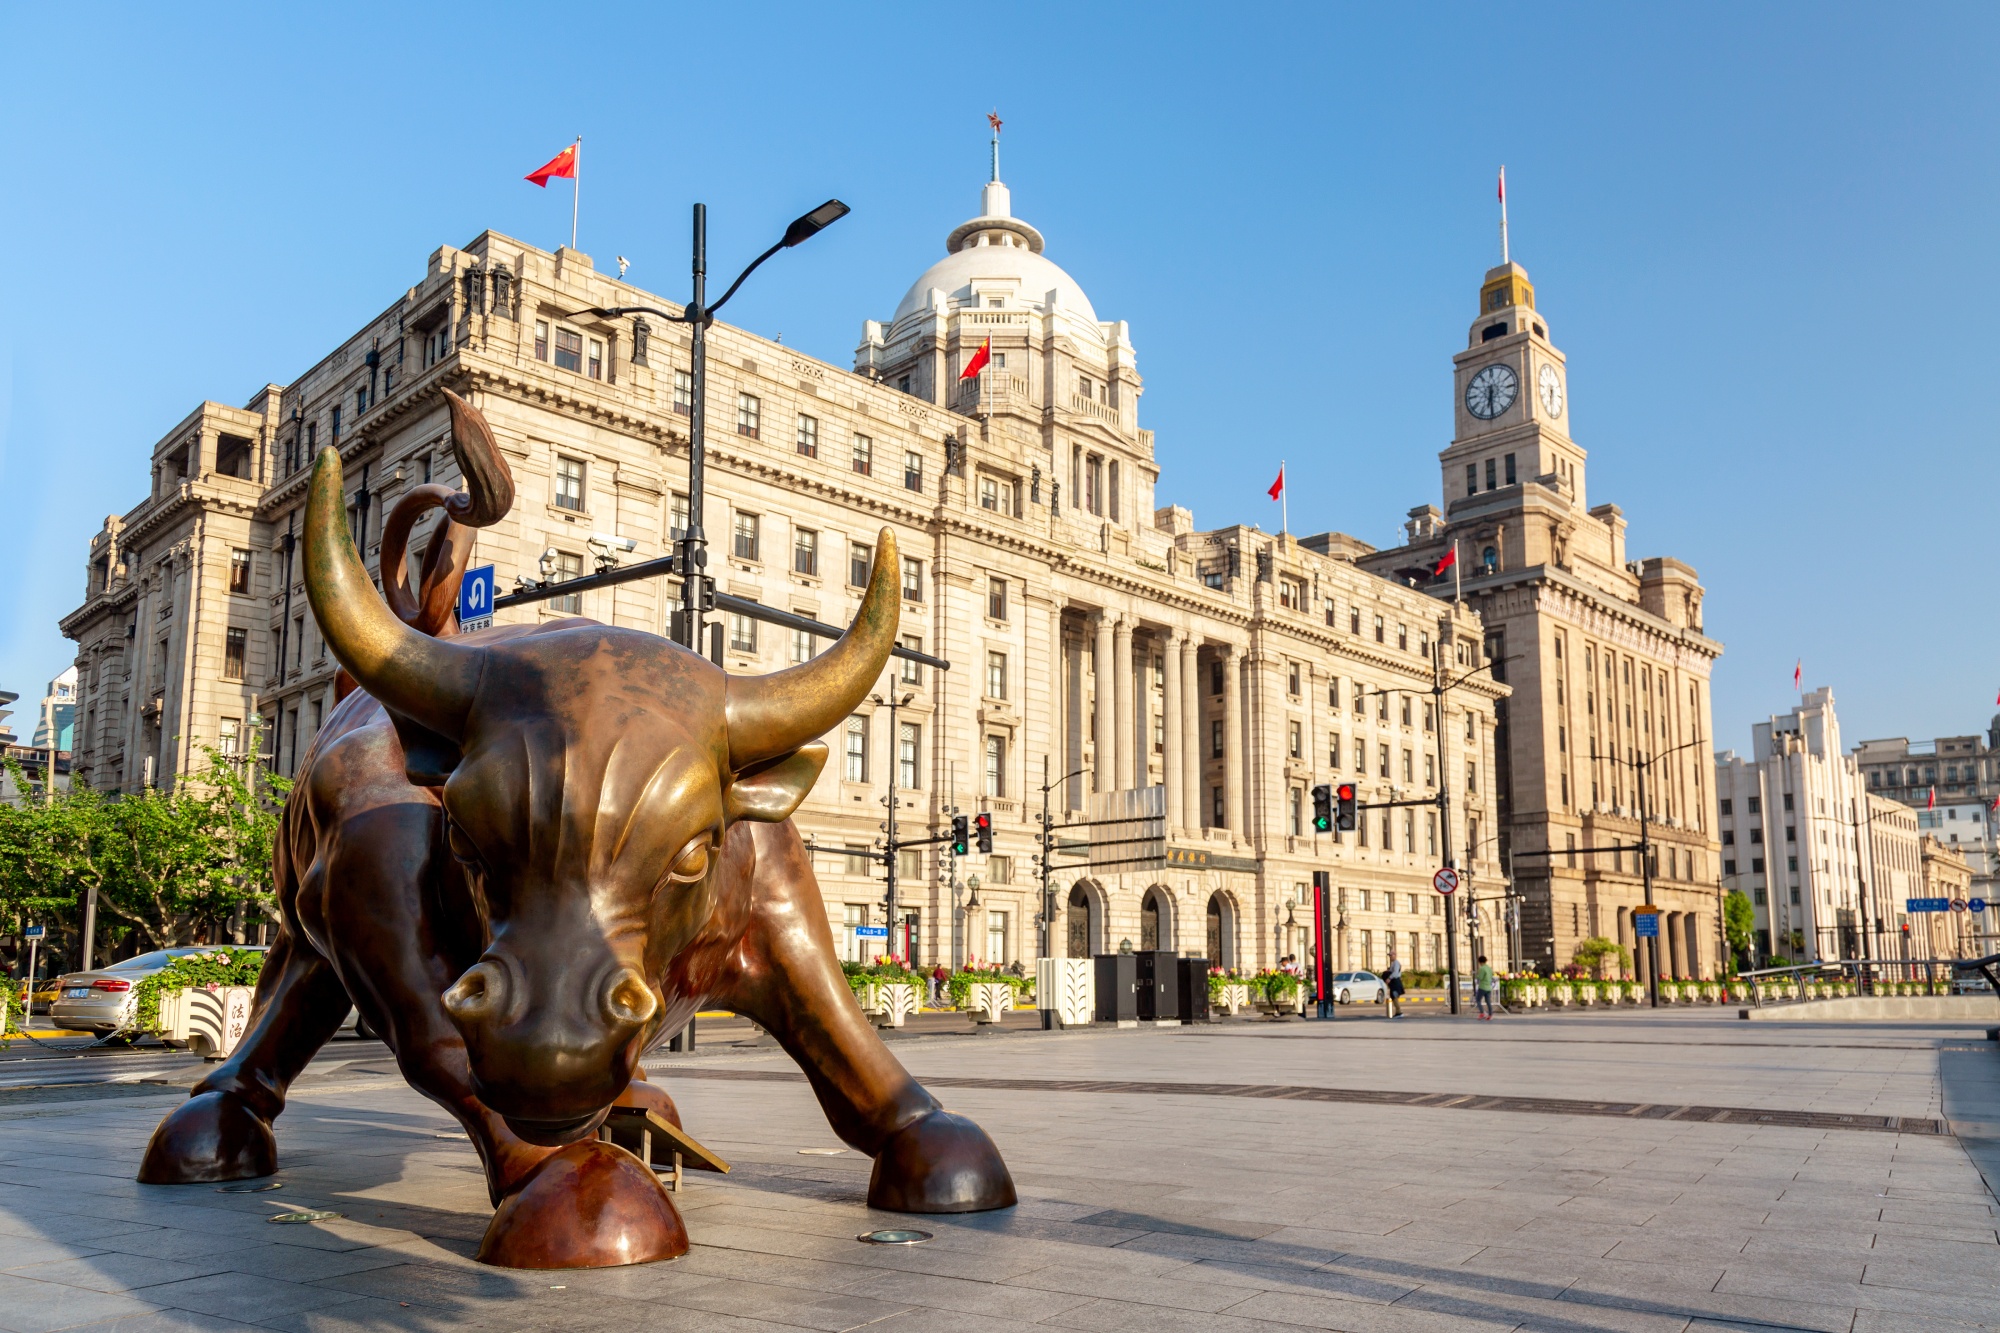
Wall Street is showing signs of AI credit fatigue that has spilled over to global indices. China stocks have not been spared, but we see reasons to be optimistic.
China’s macroeconomic slowdown, vis-à-vis a surge in tech stocks, have remained the key drivers of the economy since late 2025. Between July to September, however, tech stocks were the biggest dampeners across stock markets amid some nervousness about artificial intelligence or AI-related financing after a deluge of debt issuances over the past year.
China, which is locked in an AI rat race with the US, has not been spared from this correction as tech shares slipped. Is the AI tailwind short-lived for Chinese equities? We think not.
Tech listings up
Despite a challenging global financial landscape, high-technology companies in China have found 2026 a good time to go public. Graph 1 illustrates a surge in IPOs among IT companies in both the Hong Kong and Mainland China stock markets between January-September of this year compared to the same period in 2025. Tech IPOs in Hong Kong have surged to 33 listings year-to-date compared to seven a year ago based on PitchBook data, a level nearly equal to non-tech listings over the same period. Similarly, 21 IT companies went public in China between 1 January-15 September versus eight the prior year, although non-tech IPOs dominated stock market debuts so far.

Among the notable listing debuts this year is ChangXin Memory Technologies (CXMT), a memory chip manufacturer largely used for electronic devices and, most recently, for AI applications. At its July IPO at the Shanghai exchange, CXMT’s valuation jumped from its listing price of RMB 8.66 (USD 1.29) to RMB 49 (USD 7.30) on the same day and climbed further to RMB 54.22 (USD 8.08) by 15 September. Another is Enflame, widely dubbed as Nvidia’s rival in the global chipmaking industry, which saw its share price more than triple in less than a week after its 11 September debut.
We forecast more Chinese chipmakers to strike while the iron is hot and pursue their own IPOs over the next year amid an exponential growth in the demand for semiconductors. We are also anticipating the subsequent listings of software developers, including those behind agentic AI tools – DeepSeek and Alibaba’s QwenAI are only some examples (rather than stock picks) – to perk up the Chinese stock markets well into 2027.
China stocks correction
Despite the upbeat listing activity, China stocks have not been spared by the global tech selloff in the third quarter. This largely due to concerns about overcrowded investments and lending towards the AI buildout, missed profit or revenue expectations, and most recently, a call from executives of AI companies to slow down software development to prioritise safety. Graph 2 captures the sharp swings of tech stocks listed on the Shanghai Stock Exchange (SSE) relative to the composite index, which tracks all shares on that bourse.

The SSE 180 Information Technology Sector index declined by 29 per cent between July to mid-September, against a softer 4.5 per cent slide of the SSE Composite index. It bears noting, however, that the tech sub-index remains sharply higher year-to-date against a flattish performance for the main index. The same is true for US stocks: the NASDAQ-100 Technology Sector index slid by over 6 per cent so far this quarter but is still up by 36 per cent year-to-date to outperform the main index.
We take the longer view at Lundgreen’s, which is why we consider the decline in tech stock valuations as a brief correction rather than a collapse. The correction comes months after market overexcitement towards AI prospects since 2025, likely for profit-taking.
With the market’s shiny new toy now chipped and faded in some corners, investors are now getting a closer look. This allows them to be more selective in the AI segments they invest in, thus the resulting market rotation: amid uncertainty, investors tend to gravitate towards earnings and visible growth such as new orders. We also find that this is increasingly true, and within reason, for shifting sentiment across China stocks.
However, we take exception to the Chinese government’s deployment of a “national team,” wherein state-owned investment funds use public money to buy into domestic A-shares to prop up their valuations. This was most recently exercised in July, with nearly USD 9 billion deployed towards stock buybacks and re-lending to supposedly stabilise the domestic stock market. One look at Graph 2 will show that any positive impact had been short-lived, as the free hand of global open market trading ultimately guided share prices lower in succeeding weeks. We think this amount could have been better spent elsewhere – such as the provision of additional social benefits or direct subsidies to support consumption – rather than on countering the ebb and flow of the equities market. This surely does not help assuage investor nervousness at all and may even do the opposite, as government intervention is often frowned upon.
China’s interventionist tactic is discouraging, but we continue to see compelling opportunities for Chinese equities given the strong growth potential of companies and undervalued assets. We balance these concerns by investing in China stocks listed outside the Mainland, which has been our strategy at our own Lundgreen’s Invest-China Fund.
China’s head-to-head race with the US in the AI space will continue fuel rising valuations for tech shares over the next few years. Amid greater global market uncertainty, we remain convinced that increasing exposures to developing Asia, particularly in growth centres like China, is the best approach to maximise growth in one’s portfolio.